PMRY: Pradhan Mantri Rozgar Yojana
Thank you! Your application has been submitted.
Pradhan Mantri Rozgar Yojana (PMRY) is designed to create self-employment opportunities that are sustainable to 10 lakh unemployed youth who are educated. The scheme provides funding assistance for economically viable activities that are inclusive of agricultural and allied activities.
Pradhan Mantri Rozgar Yojana (PMRY)
Pradhan Mantri Rozgar Yojana (PMRY) was launched by the Government of India to provide sustainable self-employment opportunities to 10 lakh educated unemployed youth and women in India. It was launched in 1993, PRMY initiated this cause by offering financial assistance in starting one’s own enterprise in the trade, manufacturing and service sectors, as it helps in setting up Micro Enterprises and offering employment to educated unemployed youth.
Overview of the PMRY Scheme:
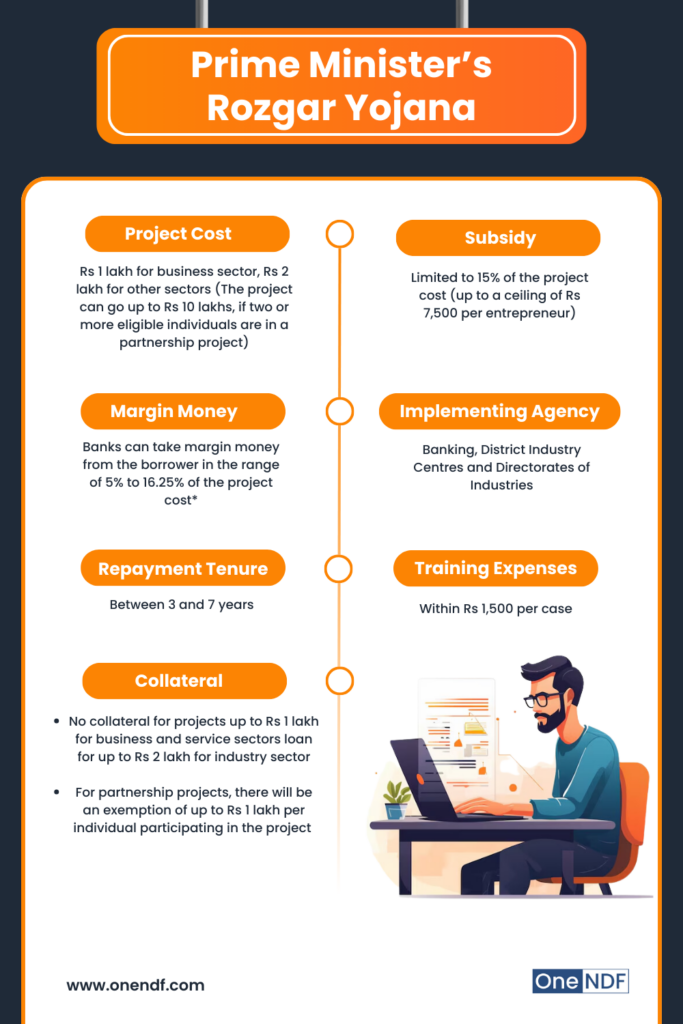
Table of Contents
Aim of PMRY Scheme
- PMRY aims to create a whooping 7 lakh micro-enterprises and ventures through the induction of business/service ventures over a duration of two years and six months.
- Small Scale Industries (SSI) will tap into a vision for utilising local resources and other technologies for productive pursuits and tapping micro-level local markets. There will be zero collateral required for projects up to Rs 1 lakh as well.
PMRY Loan Interest Rate
Interest Rate Range
Min 14% and Max 20% (Approx)
Processing Fee
Up to 2% of the loan amount
Prepayment Charges
Up to 4% of the outstanding principal
Eligibility Criteria/Parameters of PMRY
The eligibility criteria to be met in order to take a loan under the PMRY scheme follows:
- Age: The applicant should be between 18 and 35 years of age. There is a relaxation of 10 years for SC/ST candidates, women, ex-servicemen and physically challenged that is up to the age of 45 years.
- Education: The applicant must have cleared the 8th standard.
- Interest Rate: Normal interest rate shall be charged.
- Repayment Schedule: Between 3 to 7 years after an initial moratorium.
- Family Income: The income of the individual’s family should not be above Rs 40,000/month. This includes the income of the individual and spouse or the income of parents.
- Residence: Permanent resident of the area for at least 3 years.
- Loan Default: The applicant should not have been a loan defaulter in the past. He/She should not be linked to other subsidy-linked government schemes as well.
- Collateral: No collateral for project up to Rs 1 lakh. Exemption from collateral in case of partnership projects will also be limited to an amount of Rs 1 lakh per person participating in the project.
- Reservation: Preference should be given to weaker sections including women. The scheme provides 22.5% reservation for SC/ST and 27% for other Backward Class (OBCs). In case SC/ST/OBC candidates are not available, States/UTs Government will be competent to consider other categories of candidates under PMRY.
Also Read: Business Loan Eligibility
Documents Required
Given below is the list of documents you will have to submit in order to avail this government scheme:
- Duly filled application form with passport-sized photographs
- EDP Certified
- A copy of the proposed project profile
- Proof of Identity which includes PAN Card, Aadhaar Card, Driver’s License, Passport
- Experience, Qualification and Technical Certificates
- Proof of Date of Birth (SSC certificate or TC from school were studied)
- Proof of residence for 3 years, ration card or any other documents which provides a proof of your residency
- Income certificate issued by MRO (Mandal Revenue Officer)
- Caste certificate issued by MRO, if applicable
- Any other document required by the lender.
Benefits of PMRY Scheme
The PMRY comes with many benefits such as:
- The project cost for the business sector is Rs 1 lakh and Rs 2 lakh for other sectors.
- The subsidy is limited to 15% of the project cost (ceiling up to Rs 7,500).
- No collateral is required for projects up to Rs 1 lakh.
- For partnership projects, an exemption of up to Rs 1 lakh per individual taking part in the project.
- The repayment tenor under the PMRY is 3-7 years and that also after the end of the moratorium period.
- The training expenses are within Rs 2,000 per case.
Also Read: What is Udyam Registration Certificate?
Features of PMRY Scheme
- Training provided to borrowers for 15-20 days to ensure the setting up of their businesses.
- Development Commissioner (Small-scale Industries) or DCSSI under the Ministry of Small-Scale, Rural and Agro Industries is the primary body of this scheme/
- The Director of Industries implements the scheme at the State level except for the four metropolitan cities of the country
- Every Quarter, the State Level PMRY Committee monitors the progress of the scheme.
- Implementing agencies of this scheme are the metropolitan cities of the country.
- To expand their coverage areas of small tea gardens, fishing, poultry, piggery and horticulture.
- Easy Equated Monthly Instalments (EMIs) for borrower’s business initialization.
Also Read: Unsecured Business Loans
Implementation of PMRY Scheme
- The DCSSI fixes the target for the year starting from April to March. The body, depending on the population, unemployment, backwardness of the area, etc decides the targets who will be closely monitored by the body.
- The state targets are allocated by the state government to all District Industries Centres (DIC) of the district.
- The banks along with the DICs will play an important role in the implementation of the loan scheme. The Chief General Manager, RPCD of Reserve Bank of India will also be kept in loop regarding the targets allocated by the state government to the respective DICs, so that the lenders can issue fixed guidelines and funds to the lead banks of the states.
- The next step will be to invite the people to apply for the PMRY loans. An application form will be available at the DIC, local banks and with the local Industry Promotion Officers of the concerned areas. The application form will require the candidate to fill in their basic details.
- The interview of the candidates which will be conducted by a task force committee constituted by The GM and the DIC.
- After this, selected candidates will be provided with necessary training. The GM and DIC are responsible to provide the selected candidates the necessary training and give them materials based on that, so that they can understand the technicalities required to run their own organisation. The training period is 15 to 20 working days for candidates setting up industry sectors and 7 to 10 working days for the business/service sector.
- The selected candidates after the completion of the training will be monitored closely by the bodies who have provided the PMRY loan. The District will provide the information on sanctions, disbursements, training, grounding and recovery of loan sanctioned and prescribe them on a monthly, quarterly and on a yearly basis to the Commissioner of Industries, who will prepare the final report for the state government.
How to Apply for a PMRY Loan
The steps to apply for a PMRY Loan are as follows:
- After finalising the project idea, along with the project profile the applicant has to fill the form and duly submit it enclosing the necessary documents and photographs at the DIC or at the local bank.
- All the applications received at DICs and banks are thoroughly monitored and selected applicants are called for an interview. In order to facilitate the applicants, the interviews are planned at major convenient places of the district so that candidates can attend the interviews at a place that is near to their place of residence.
- Most of the prospective entrepreneurs desiring to avail the benefits of this scheme fail to utilise it, due to lack of proper guidance and awareness about the modalities and formalities to be followed to avail the scheme. With an aim to fill this avoid a step by step guidelines are explained about the eligibility relating to age, minimum educational qualifications, family income, resident proof and cast certificate for SC/ST/OBC either by DIC/SISI/Local banks. A person willing to apply for PMRY should check out all these aspects and should produce proof for all these parameters while applying for the scheme.
- One can apply any time during the year. But the best time would be between April to June of the year. The normal practice is to hold PMRY interviews in three phases in a year in all the districts.
- The Task Force Committee conducts the interview and selects the candidates for the bank loan.
Modifications and New Developments in the PMRY Scheme
- The educational qualifications for eligibility under the scheme have been reduced to 8th class from 10th class
- The scheme will offer coverage for the agriculture and the allied sectors while excluding direct agricultural activities including purchase and manure along with raising crops and other activities.
- The upper age limit has been raised by 10 years up to 45 years from 35 years for people falling in SC/STs, women, ex-servicemen and physically challenged people.
- Group financing eligibility has been provided up to a sum of Rs 5 lakhs.
How OneNDF Can Help You
OneNDF provides essential funding for applicants seeking business loans under the PMRY scheme, as it helps to connect businesses and individuals with the right lenders to meet their specific needs. Offering you the right guidance in business planning and financial management, along with flexible loan terms and streamlined approval processes.
FAQs
PMRY Stands for Prime Minister’s Rozgar Yojana.
The subsidy offered under PMRY is 15% of the project cost, a maximum of Rs 7,500.
The borrower or applicant should comply with some statutory formalities before a project grounding. These are as follows:
- Arrange for the margin money
- Take permission from a local body such as the Municipality or the Panchayat for the start of the project
- Arrange for collateral security, if required
- Get clearance from the Pollution Control Board
- Get the sales tax registration
- Register with the DIC as a micro sector unit. This will help in availing the State Government Incentives
- Obtain other statutory clearances falling under the Labour Act, Factories Act, Central Excise and Boilers Act, if applicable.
The repayment schedule to be followed by the applicant should be between 3 to 7 years after the initial moratorium period.
The applicant should have studied and passed 8th class to be eligible as per the sole discretion of PMRY.
There is no requirement of collateral for projects up to Rs 1 lakh.
The minimum age criteria for the applicant should be 18 years and the maximum of 35 years and in case of SC/ST candidates, women, ex-servicemen and physically challenged individuals the maximum age criteria is up to 45 years.
The Pradhan Mantri Rozgar Yojana (PMRY) has been implemented since 1993. PMRY is a scheme that has been designed to come up and provide sustainable self-employment opportunities. Preference is given to weaker sections, and it also includes women. The scheme covers 22.5% reservation for SC/ST and 27% for OBC.
Business Loan Other Pages
Business Loan by Banks & NBFCs